Simple budgeting strategies to manage your finances with confidence
Simple budgeting strategies for real life. Learn easy ways to set goals, track spending, and choose a method that fits your lifestyle.
Ever feel like your money disappears before the month ends? Managing day-to-day spending can seem overwhelming, especially if you’re starting from scratch. Many people search for the perfect system, but the answer is almost always “keep it simple.”
A growing number of Americans say money stress is a top concern. Learning simple budgeting strategies is one of the clearest ways to reduce anxiety and regain control, according to a range of financial wellness resources. Knowing how to budget isn’t just about restriction, it’s about making your money work for your real goals.
But here’s the catch: most online tips offer generic solutions or “one-size-fits-all” tricks. They skip the important details: choosing a method that fits your lifestyle, tracking the right way, and actually adjusting as life changes. Many quick budgeting fixes don’t last.
This article cuts through the noise. You’ll get practical, research-backed advice on setting goals, choosing a method that fits, and making simple systems stick for the long haul. Let’s make budgeting something you can trust, not dread.
Setting clear financial goals
Clear financial goals are the backbone of every smart budget. They keep you motivated and make saving feel less overwhelming. Let’s break down how goal-setting works in practice.
Short-term vs. long-term goals
Short-term and long-term goals solve different needs.
Short-term goals usually take a year or less. These often include building an emergency fund or paying off credit card debt. Long-term goals, like retirement or a home purchase, might take five years or more.
Experts suggest people new to budgeting put 80–90% of extra cash toward short-term stability first. For example, adding just $10 a week to savings can quickly build your safety net. Use high-yield savings for short-term, and consider CDs or investment accounts for long-term.
Linking goals to your budget
Connect your goals to real numbers in your budget.
Start by counting your true income minus your needs. Then figure out how much you can set aside for each goal. Try the three-bucket approach: one for essentials, one for short-term goals, one for a main long-term goal.
Make goals specific, like “$1,000 by December”, instead of vague hopes. If something changes, adjust your deadline, but keep your goal alive. That way your budget always fits your priorities.
Prioritizing your financial needs
Start with what matters most right now.
You can’t do it all at once. Tackle urgent needs first: basic expenses, then an emergency fund, then future plans.
Most planners say pick one short-term and one long-term goal to focus on at a time. Automate savings if you can, so you don’t forget. Ranking your goals by importance, not just desire, helps you make progress without feeling lost.
Choosing the right budgeting method
Picking the right budgeting method is not one-size-fits-all. The best fit depends on your habits and goals. Here’s how three popular strategies work in real life.
Overview of popular approaches
The 50/30/20 rule splits your money by needs, wants, and savings.
You put 50% of income toward essentials, 30% for fun or wants, and 20% for saving or paying down debt. Other common methods include zero-based budgeting, where every dollar gets a job, and the envelope system, which uses cash in labeled envelopes. Choose a method that targets your main challenge: saving, overspending, or tracking cash flow.
Zero-based budgeting explained simply
Zero-based budgeting means you assign every dollar somewhere each month.
If you bring home $4,000, you plan out where it all goes, rent, food, emergencies, fun, until your budget totals zero. This system makes you deliberate and helps spot waste. It’s ideal if you like details and want a true “intentional spending plan.” List expenses, savings goals, and keep adjusting until nothing’s left unassigned.
When to use the envelope system
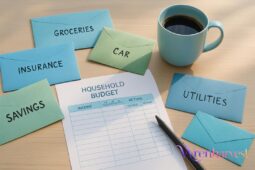
The envelope system is best if you overspend and want clear limits.
You decide on set cash amounts for things like groceries and dining out, divide the cash by envelope, and only use what’s inside. For example, put $300 each month in a “Dining” envelope. When it’s empty, that category is done for the month. This works great for people who need a physical spending stop and don’t like apps.
Tracking income and expenses easily
The simplest way to get control of your money is to track income and expenses every week. Free apps and easy systems make it less stressful than ever. Here’s how to make it work.
Best free tools and apps
Using free tools and apps can make tracking almost automatic.
NerdWallet gives a full budgeting experience for free. Empower links your bank accounts and investments. Goodbudget works for envelope-style budgets. For freelancers, Wave is built for irregular paychecks. If you like privacy, try Finny for manual entry or just use a Google Sheet. Pick the tool you’ll check every week.
Habit tips for tracking success
Make tracking a weekly habit and keep it simple.
Set a calendar reminder to review spending the same day each week. Experts say only about 1 in 3 people check their budget monthly, but tracking more often helps you spot overspending early. Write down or log every expense, even small ones, and sort them by “needs” and “wants.” That’s how you build habits that stick.
Dealing with irregular income
Handle irregular income by giving every dollar a job up front.
If you’re a freelancer or have side gigs, use Zero-based budgeting methods or envelope categories. Wave lets you track unpredictable deposits and assign each one to bills, savings, or fun. Set minimum budgets for “must pay” expenses. In good months, fill envelopes for emergencies or goals so you’re covered when work slows down.
Adjusting your budget as needs change
Budgets are meant to change when your life changes. Regular check-ins help you catch surprises and keep your plan real.
Responding to unexpected expenses
Build an emergency fund and cut back when things pop up.
Try to save a buffer, aim for 3–6 months’ expenses in a savings account. If an unexpected bill hits, like a car repair, shift spending from non-essentials (e.g., skip takeout that week) to cover it. Even small surprises need quick action, so plan for them in advance wherever possible.
How to review budget monthly
Review monthly to find spending drifts and adjust early.
Use three months of statements to spot trends. If any category is over 10% off budget, dig in and decide if you need to lower spending or adjust your target. An easy monthly review could prevent problems from growing big.
Signals it’s time to revise your plan
Watch for new life events or big changes in spending patterns.
If your income drops, you start overspending, or a one-time bill becomes a regular thing, it’s time to reset your plan. Remember, sometimes the “old budget is dead” and you need a mini-budget for a few months while life settles down again.
Building lifelong financial confidence: Putting your simple budget into action
Building real financial confidence comes from small, repeatable actions, not luck or big breakthroughs.
When you follow your simple budget each month, you build momentum and see progress. Research suggests that aiming to save 20% of your take-home pay and working toward an emergency fund covering 3–6 months of expenses creates a cushion that eases money stress.
A practical way to start is the 30-day spending audit: print your statements, sort expenses by needs and wants, and spot patterns. Experts say tracking every dollar, even just once a month, makes your decisions more intentional. Try automating $50 from each paycheck into savings and add any extra cash, like $20 if you find yourself under budget, straight toward debt or your next big goal.
Review your budget monthly, then quarterly. If your life shifts, let your plan shift too. The 50/30/20 rule is a simple framework that covers real needs, fun spending, and savings or debt. Confidence grows as you make each money move on purpose, not just on hope. Over time, these habits protect you and turn budgeting from a chore into a source of calm and freedom.
Key Takeaways
This article offers actionable steps for mastering simple budgeting strategies and building lifelong financial confidence.
- Set clear financial goals: Distinguish between short-term and long-term needs and assign specific targets to each.
- Choose the right budgeting method: Methods like the 50/30/20 rule, zero-based budgeting, and the envelope system help tailor your budget to your lifestyle.
- Track income and expenses: Use free apps such as NerdWallet, Empower, or Goodbudget and review your spending weekly for best results.
- Make habits stick: Consistent check-ins—ideally weekly or monthly—are key, since fewer than one-third of people check their budget monthly.
- Prepare for surprises: Build an emergency fund equal to 3–6 months’ expenses and adjust your budget quickly when unexpected costs arise.
- Adapt your plan: Regularly review your budget and revise it if you see categories drifting more than 10% or if your life circumstances change.
- Automate your savings: Aim to save 20% of your income by automating transfers and adding extra cash to savings or debt payments.
- Practice builds confidence: Financial confidence grows from repeating small, intentional money habits—not from dramatic changes.
The main takeaway: Follow a simple but flexible budget and adjust as needed, and you’ll take real control of your financial future.