Step by step budgeting for effective money management and saving goals
Step by step budgeting empowers you to manage money with confidence. Learn practical techniques for tracking expenses, setting goals, and building a lasting savings habit.
Ever feel like your paycheck disappears before you even notice? You’re not alone. Most people want to save more and stress less about money, but knowing where to start is the tricky part. That’s where a step-by-step approach to budgeting can be a game-changer.
Managing your money gets easier once you break it down. According to financial experts, creating (and sticking to) a budget is one of the most effective ways to reach your goals, whether that’s paying off debt, building up savings, or just making sure all the bills get paid. The challenge is often getting started. Step by step budgeting gives you a roadmap, so you don’t have to guess.
But here’s the thing: a lot of advice ignores the messiness of real life. Generic budgeting tips or one-size-fits-all templates usually don’t work for long. Sustainable results come from tailoring your plan, tracking your actual spending, and using tools that fit your habits.
This article cuts through the clutter. You’ll learn how to organize your income and expenses, pick personal goals, build a budget plan you can stick with, and make real progress toward saving, even if money’s tight. Ready to take charge of your finances one clear step at a time?
Understanding your income and expenses
Getting a handle on your money starts with a simple job: know what you earn and what you spend. This is the real foundation of good budgeting, and it only works if you’re honest with your numbers.
Identifying reliable income sources
Total monthly income matters most. Include paychecks after taxes, steady freelance gigs, rental checks, benefits, or any side hustle. For money that’s less predictable, divide the total you got last year by 12 to estimate what you get each month.
If you receive lump-sum payments, like student aid or occasional bonuses, spread them out for a more accurate monthly average. Only count extra cash in your budget once you actually have it, not when you expect it.
Tip: Track what comes in using a spreadsheet or a free budgeting app so you don’t miss small amounts you might forget about.
Differentiating fixed and variable expenses
Fixed vs. variable expenses is key. Fixed means the same every month: rent or mortgage, car payments, insurance. Variable expenses change a lot: groceries, gas, eating out, and fun money. Don’t forget split out ‘wants’, like subscriptions or entertainment, from true needs.
The best way to spot your patterns? Review the last 2-3 months of bank and card statements. If you’re a tech fan, try apps that sort these categories automatically.
Tip: Always fill your “needs” first, then see what’s left for “wants.”
Tallying your actual monthly expenses
Tracking actual spending habits gives you the real picture. Write down every single purchase and bill, no matter how small. Use your phone, a notebook, or an app.
Add up average spending for each category, using at least two months of records. Subtract total expenses from your income, if the result is negative, it’s time to cut back.
Expert advice: Use a spending tracker so nothing slips through the cracks, and aim to build up emergency savings worth three to six months of expenses.
Setting realistic financial goals
Setting goals is how you give your money a real purpose. But for goals to work, you need more than wishful thinking. The key is to be honest about what’s possible, and to pick targets you can actually reach.
Short-term versus long-term goals
Divide your goals into short-term vs. long-term. Short-term means “in the next year,” like saving for new tires or paying down a small credit card balance. Long-term goals might be five years out, like buying a home or planning for retirement.
Many experts recommend putting 80–90% of extra cash toward short-term goals and debt, and the rest into long-term plans. Example: Set aside $10 a week to build an emergency fund, and put a smaller amount toward retirement savings. Breaking large goals into milestones helps you see progress faster.
Aligning goals with your values
Your goals should align with your values. Why aim for a vacation, a new car, or early retirement? Because it fits what matters most to you, like family, security, or health. Ask yourself who, what, when, where, and why for each goal.
For example, saving for a family vacation isn’t just about travel, it’s about time together. “Focus on the reasons your goals are important.” That makes it easier to stick with your plan when life gets busy.
Prioritizing savings and debt repayments
Build an emergency fund and pay down debt first. Think of your goals as buckets: one for basics (like rent), one for your top 1–3 short-term targets, and one for your dream goal in the future.
Start with an emergency fund, most experts suggest at least three months of expenses. Use the 50/30/20 rule to divide your income: 50% for needs, 30% for wants, 20% for savings and debt repayment. Make sure every goal fits realistically in your monthly budget before committing to it.
Creating a simple monthly budget plan
Making a budget shouldn’t be complicated. It’s about building a plan you can actually use, and sticking to it, even when things change. Your goal? Make your money work for you every month, not just on paper.
Selecting a budgeting method (envelope, 50/30/20, zero-based)
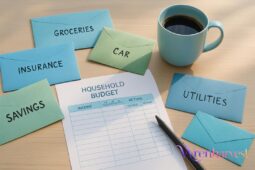
The 50/30/20 rule is great for simplicity. Use half your income for needs, 30% for wants, and 20% for savings or debt. The zero-based method says every dollar has a job: you spend (or save) all your income, ending at zero. Prefer cash? The envelope method gives each category a physical limit, once the envelope’s empty, you stop spending.
Experts suggest reviewing your last 2-3 months of spending before choosing a method. Try each for a month and see what helps you stay on track.
Allocating funds to key categories
Always cover fixed expenses and savings first. Start with things like rent, utilities, and loan payments. Next, add variable expenses like groceries and entertainment. A sample $4,000 net income would be split into $2,000 (needs), $1,200 (wants), and $800 (savings/debt) under the 50/30/20 plan.
Quick tip: Put savings or debt payments as line items, don’t just leave “what’s left over.” Give every dollar a real job.
Planning for unexpected costs
Add a budget buffer to every plan. This is a small cushion, maybe $50 to $100 each month, that keeps you from dipping into savings when costs spike. If you have unpredictable bills, average those out over the year.
If you find expenses are higher than income, cut “wants” or other non-essentials right away. Even a small buffer helps you stay in control, not caught off guard.
Tracking your spending habits
You can’t fix what you can’t see. That’s why tracking your spending habits is one of the most powerful things you can do for your budget. Even small changes in how you monitor money can make a real difference.
Using digital budgeting tools
Digital budgeting tools make things easier. Apps like Mint, YNAB, or Capital One’s Map Your Spend link straight to your bank. They track every dollar, sort your spending into categories, and even send overspending alerts if you’re close to your limit.
Feature to try: Find an app with expense categorization and goal tracking. Some apps, like Spend Setter℠, show you what percent of your budget you’ve used, so you can adjust before you overspend.
Reviewing expenses weekly
Weekly reviews help catch problems early. Set aside a few minutes every Sunday to check last week’s expenses. This habit can reveal patterns, like how often you grab takeout or extra coffees.
Case in point: A student using Goodbudget reduced grocery costs by 15% in one month by tracking snacks. Regular reviews keep you honest and stop overspending before it snowballs.
Spotting and addressing overspending patterns
Look for overspending patterns with reporting tools. Many apps can show where you’re spending too much, flag duplicate charges, or alert you about big tips. Simplifi by Quicken and PocketGuard both highlight problem areas with simple reports.
Financial expert Dave Ramsey says, “Tracking every dollar exposes impulse buys.” By adjusting as soon as alerts fire, you avoid costly habits and keep your budget on track.
Adjusting your budget for long-term success
Budgeting isn’t “set it and forget it.” Life changes, and your financial plan should change with it. Keeping your budget working means checking in and making small shifts as things come up.
When to revisit and update your budget
Quarterly budget reviews keep you on track. Revisit your numbers every three months, or monthly when things are unstable. If your income or expenses change, update your budget right away. For anyone with variable pay, plan around your lowest expected income for extra safety.
If you get a new job or face a big bill (like moving), don’t wait, adjust your plan that month. Reviewing often helps you avoid surprises and see progress.
Staying flexible as goals change
Allocate for surprises and change your plan if needed. Build in a 5% buffer for things you can’t predict. If you get a raise, try saving 50% of it instead of spending it all. Practice scenario planning: Imagine the best, worst, and most likely cases for your money so you’re never blindsided.
Life goals can shift, maybe you need to save for a new car instead of a vacation. Just tweak your categories as your priorities change.
Building habits for lasting financial health
Automate savings and know your spending triggers. Set up “pay yourself first” auto-transfers to savings or retirement when your paycheck hits. List essentials, debt minimums, and emergency savings as top priorities before anything fun.
Notice what makes you spend more, like stress or boredom. Swapping these triggers for healthier routines can help you stay on track, and over time, these habits will become second nature.
From budgeting basics to confident money management: your sustainable path forward
The direct answer: budgeting basics are your launchpad for confident, sustainable money management. Mastering simple tools, like the 50/30/20 rule, helps put every dollar to work for your future. That’s how you build steady progress and real financial peace.
To get started, track your expenses for at least four weeks. This splits your spending into fixed vs. variable expenses so you see where your money really goes. Begin building your emergency fund, starting small, with $500 or $1,000, is a win. Automate savings on payday to build the habit before you even miss the cash.
Experts say consistent reviews matter. Check your budget monthly and tweak things after life changes, like a raise or bigger rent. For tackling debt, the debt snowball method can deliver fast wins and keep your motivation high.
Make your goals clear and realistic, and give them deadlines. And don’t skip fun: setting aside 5–10% of income avoids burnout. Northwestern University’s advice? “Be honest with yourself…figure out what really matters.” That’s how budgeting moves from a chore to your favorite tool for financial confidence.
Key Takeaways
Here are the key strategies and insights for step-by-step budgeting and effective money management:
- Know your income and expenses: Begin by tracking all sources of income and every category of spending to create a clear financial picture.
- Set realistic financial goals: Divide goals into short- and long-term, use the SMART criteria, and align them with your personal values for greater motivation.
- Choose the right budgeting method: Methods like the 50/30/20 rule, envelope system, or zero-based budget make it easier to allocate funds and stay organized.
- Always budget for savings and emergencies: Aim to save at least 20% of income and start with an emergency fund of $500–$1,000 to build resilience.
- Track and review spending regularly: Digital tools and apps help monitor expenses, identify overspending patterns, and can increase savings by up to 40%.
- Stay flexible and update your budget: Review your plan quarterly or after life changes, and adjust categories or amounts as goals evolve.
- Automate and build habits: Automate transfers for savings and debt payments, and pay yourself first to establish long-term financial health.
- Include fun money to avoid burnout: Set aside 5–10% of your income for enjoyable activities to keep your budget sustainable.
Ultimately, a step-by-step approach to budgeting transforms money management from a chore into a powerful tool for sustainable financial confidence.